CBAM Default vs Actual Emissions: Data Requirements

Short answer: CBAM default values and verified actual emissions are different reporting routes under the applicable rules. A Product Carbon Footprint (PCF) can provide useful source data, but its final result is not automatically suitable for a CBAM declaration. Check the covered goods, installation, production route, reporting period, calculation boundary, and verification requirements first.
For manufacturers and exporters, the practical question is which data will help an EU customer meet its CBAM obligations. Better evidence can make an actual-emissions calculation possible. It does not guarantee a lower liability or faster customs clearance.
The timeline: 2026 imports, purchases from February 2027
The definitive CBAM regime began on 1 January 2026. According to the European Commission, certificates will be purchased through the common central platform from February 2027 onwards, including certificates corresponding to covered imports during 2026. The purchase date should not be confused with the period for which emissions data must be collected.
The Commission calculates quarterly certificate prices for 2026 and weekly prices from 2027. The published prices are EUR 75.36 per tonne of CO2 for Q1 2026 and EUR 75.28 for Q2 2026. These are period-specific prices, not a fixed rate for every shipment. Source: Commission certificate-price page.
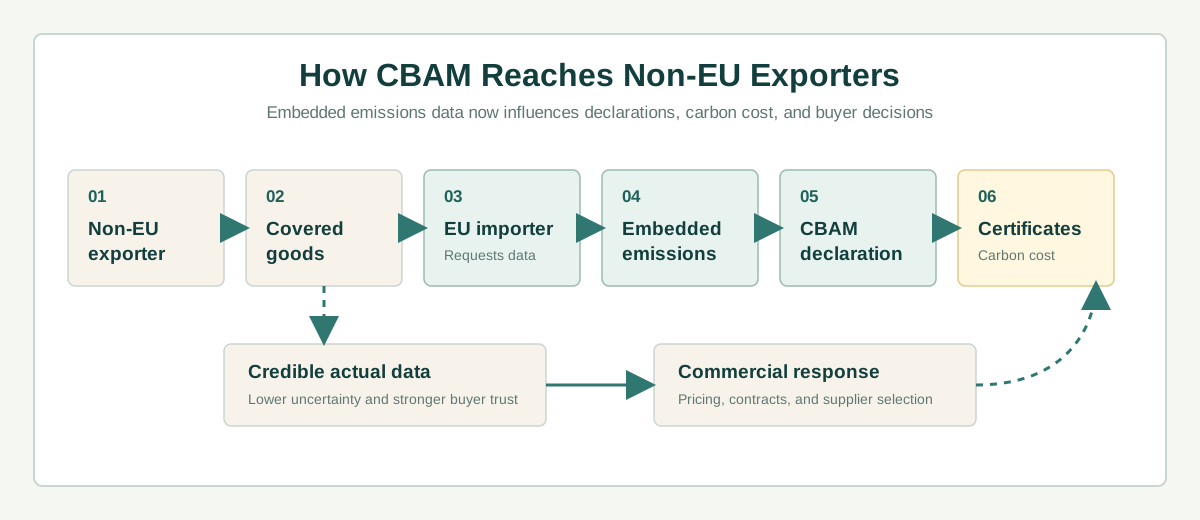
EU authorised CBAM declarants hold the declaration and surrender obligations. Non-EU producers support them with production and emissions records. Source: Commission definitive-regime guidance.
When default values and actual emissions differ
Default values are prescribed reference values used in the circumstances allowed by the rules. They should not be replaced with an arbitrary industry average or a value from an old transitional-period document.
Use the current definitive-period rules and values for the relevant goods and origin. The Commission's guidance page includes the default-value regulation and its July 2026 correction. Source: CBAM legislation and guidance.
| Route | What to establish | Main limitation |
|---|---|---|
| Applicable default values | Correct goods classification, origin, period, and permitted use of the published values | They may not reflect the actual installation's performance |
| Actual emissions | A calculation based on applicable CBAM methods, supported by production records and required verification | A supplier number or PCF label alone is insufficient |
Actual emissions may be below or above the applicable default. Compare both on the same CBAM basis before claiming a benefit. Lawful use of defaults is not, by itself, evidence that a shipment will be rejected or delayed.
A PCF is not a CBAM declaration
A PCF describes greenhouse-gas emissions for a defined product unit and life-cycle boundary. CBAM uses its own goods classification, production-system boundaries, calculation methods, and reporting requirements. For example, the treatment of direct emissions, indirect emissions, and relevant precursors depends on the goods and applicable CBAM rules.
A cradle-to-gate PCF total may include stages or assumptions that cannot simply be transferred into CBAM. Likewise, a generic secondary factor that is appropriate for PCF screening is not automatically an acceptable CBAM input.
| Existing PCF material | Potential reuse | Check before use in CBAM |
|---|---|---|
| Energy and fuel records | Activity data for the relevant installation and processes | Period, units, production boundary, and completeness |
| BOM and procurement records | Identification of materials and relevant precursors | CBAM goods definitions and precursor treatment |
| Production volumes and allocation records | Supporting records for assigning emissions to goods | Applicable calculation and allocation rules |
| Factor and evidence registers | Traceable sources for review | Methodological acceptability, versions, and verification |
| Final PCF report | Background explanation and source references | It does not replace a CBAM-specific calculation or declaration |
The Commission lists separate implementing rules for calculation methods and verification. Apply them when mapping the source records to the CBAM calculation. Source: CBAM legislation and guidance.
Prepare the right data pack
Begin by confirming the product's exact CN code and whether it falls within the applicable scope and exemptions. Broad descriptions such as “steel product” or “aluminium component” are not enough.
- Identify the goods and installation. Record the CN code, country of origin, operator, site, and production route.
- Agree the data period. Align production, energy, material, and emissions records with the required reporting period. Explain any gaps.
- Map emissions and precursors. Identify sources and precursor inputs required by the applicable method; distinguish direct and indirect emissions where relevant.
- Document the calculation. Preserve units, conversions, source records, factors, allocation choices, and reasons for estimates.
- Prepare for review. Resolve missing evidence and obtain the verification required for actual emissions under CBAM.
- Coordinate with the declarant. Agree the required fields and format with the EU customer or its representative before delivery.
For an operational starting point, see our manufacturer and exporter carbon-data workflow. It focuses on organizing records and review steps before customer handoff.
Compare costs without promising savings
Embedded emissions multiplied by a certificate price is a starting point for a scenario, not a complete CBAM liability calculation. The amount payable also depends on applicable rules, including the free-allocation adjustment and any eligible carbon price already paid in the country of production.
Use the appropriate period's price, check the deductions and adjustments, and document the assumptions. Compare the possible difference in liability with the cost of data preparation, verification, and ongoing updates. A PCF model does not guarantee lower CBAM costs.
The Commission explains the carbon-price deduction and lists the implementing rules for the free-allocation adjustment in its definitive-regime guidance and legislation library.
Build reusable records, then review each output
Keep an organized source-data library, calculation history, and evidence register. Update them when the product, site, supplier, process, energy mix, or applicable rules change. Reuse compatible records across customer PCFs and CBAM preparation, with a separate mapping and review for each purpose.
Climate Seal supports structured carbon accounting workflows that connect source files, calculations, factor records, risk signals, and audit evidence. Experts retain responsibility for methods and final decisions. Independent verification and the declarant's obligations remain separate.
Preparing a response to an EU customer? Discuss your CBAM data-preparation needs. Bring the goods classification, production location, available records, and the customer's requested reporting period.
References
Climate Seal Resources
Do you find our content useful? Get updated once a week
Receive a concise weekly digest of new articles, regulatory insights, and practical guidance.